Your read progress
Buy Now, Pay Later explained: how it affects your credit score
1 minute read
Updated 12th October 2026 | Published 12th October 2026
Buy Now, Pay Later (BNPL) enables you to spread the cost of purchases. In this article, we explain more about BNPL including how it affects your credit score and what new regulations mean for you.
What is Buy Now, Pay Later and how does it work?
Buy Now, Pay Later is short-term credit that consumers use to spread the cost of purchases across a series of instalments. These payments are often interest-free, with repayment periods typically ranging from a few weeks to several months, depending on the provider and the agreement.
Is Buy Now, Pay Later the same as a credit card?
BNPL and credit cards are both forms of credit, but they work differently.
A credit card gives you credit up to a set limit that you can use repeatedly. Interest is charged on the balance you don’t pay off. BNPL is used for a specific purchase with a fixed repayment plan.
Does Buy Now, Pay Later show up on your credit report?
This depends on the provider and the type of agreement. Historically, many short-term BNPL plans didn’t show up on credit reports, which meant missed payments were unrecorded. But now, more BNPL providers share data with UK credit reference agencies.
Check with your BNPL provider if your agreement will be reported and to which agencies.
Does Buy Now, Pay Later affect your credit score?
Yes, it can. When you apply for BNPL, the provider may carry out a soft credit search, which leaves a record on your credit report but doesn’t affect your score. But many providers now share your repayment behaviour with Experian, Equifax and TransUnion. It can reflect positively on your credit report if you consistently make payments on time.
It can damage your score if you miss payments and stay on your credit file for up to six years, making it harder to get credit in the future. Contact your BNPL provider as soon as possible if you get into financial difficulty to discuss a way forward.
What’s the difference between a soft and hard credit check with Buy Now, Pay Later?
When you apply for BNPL, the provider will carry out either a soft or hard credit search.
A soft search is an initial check of your credit file that gives the provider an overall view of your creditworthiness. It leaves a record on your report but isn’t visible to other lenders and won’t affect your credit score.
A hard search is a full credit check that’s visible to other lenders and can lower your credit score. Multiple hard searches in a short space of time can be a red flag to lenders, as it suggests you’re applying for a lot of credit.
Under FCA rules, BNPL providers must be transparent about the type of search they do, so always check before you apply.
How many Buy Now, Pay Later agreements can you have at once?
There’s no set limit on how many BNPL agreements you can have at once, providers set their own criteria and will make decisions based on their affordability assessments.
Having multiple BNPL agreements at the same time increases your total debt commitments. If you apply for a mortgage or other significant credit, lenders will look at all your existing financial commitments to assess affordability. Multiple BNPL plans could raise concerns, even if you’ve never missed a payment.
Is Buy Now, Pay Later safe to use?
In July 2026, eligible BNPL agreements came under regulation by the UK's Financial Conduct Authority (FCA), which provides more consumer protection.
BNPL companies must carry out affordability checks before offering credit. They also have to give you clear information about your repayment schedule upfront and provide support if you find yourself in financial difficulty.
You also have the right to refer a complaint to the Financial Ombudsman Service if you’re unhappy with how a provider has treated you.
Eligible BNPL agreements also benefit from Section 75 protection under the Consumer Credit Act. This means the provider is jointly liable with the retailer if something goes wrong with a purchase over a set amount.
Although you have more protection now, BNPL is still credit and has the same risks as other borrowing. Only use it when you’re confident you can make the repayments.
Expert thoughts on Buy Now, Pay Later from Smart Money People
BNPL can be a good way to spread the cost of purchases with little or no interest, but it must be used responsibly.
Before using BNPL, check if the provider carries out a hard or soft credit search and only take credit you can repay on time. Keep track of how many active agreements you have and be mindful of your BNPL agreements in the months leading up to applications for larger lines of credit like a mortgage.
Give feedback about your experience
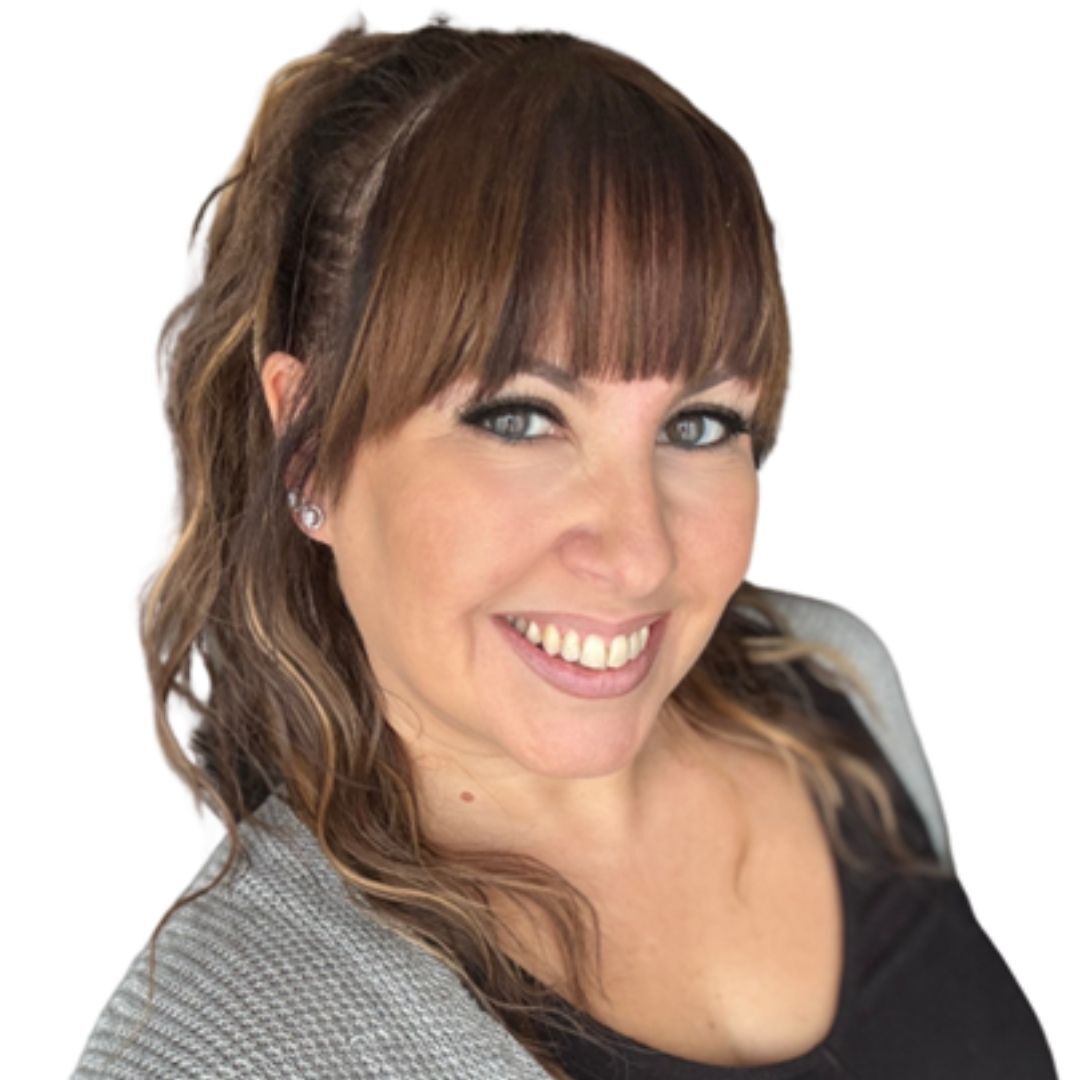
Written by Katy
Senior Content Writer
Katy joined us in 2024. She's passionate about helping others to know more about financial products so they can make smart money choices.
As Featured By
Join our mission
We use the power of consumer reviews to help increase trust and transparency in financial services and to deliver industry leading insight and events.
Write a reviewRelated smart money guides articles
View smart money guides
How is credit card interest calculated?
15th September 2025 by Errolyn
Credit scores: what you need to know
3rd August 2026 by Errolyn
Understanding debt consolidation with StepChange - why might it be a problem?
24th February 2026 by Guest author
Seven common credit card questions answered by Aqua
15th September 2025 by Guest authorExplore our other topics

News: Awards

News: Industry news

News: Smart Money People news
Blogs: Money choices